DMCI Homes · Aurora Blvd., Brgy. Marilag, Quezon City
Infina Towers
Modern Contemporary architecture in Aurora Blvd., Brgy. Marilag, Quezon City.
DMCI Homes · Aurora Blvd., Brgy. Marilag, Quezon City
Modern Contemporary architecture in Aurora Blvd., Brgy. Marilag, Quezon City.
The Community
A home that transcends city living — twin 41-storey towers balancing a dynamic metro lifestyle with earth-toned, nature-inspired calm.
This community is fully sold out by the developer. Francine can help you find resale units or similar available DMCI properties nearby.
Location & Accessibility
Infina Towers sits in Aurora Blvd., Brgy. Marilag, Quezon City — close to malls, schools, hospitals, and major transit links across Quezon City and Metro Manila.
Community Amenities
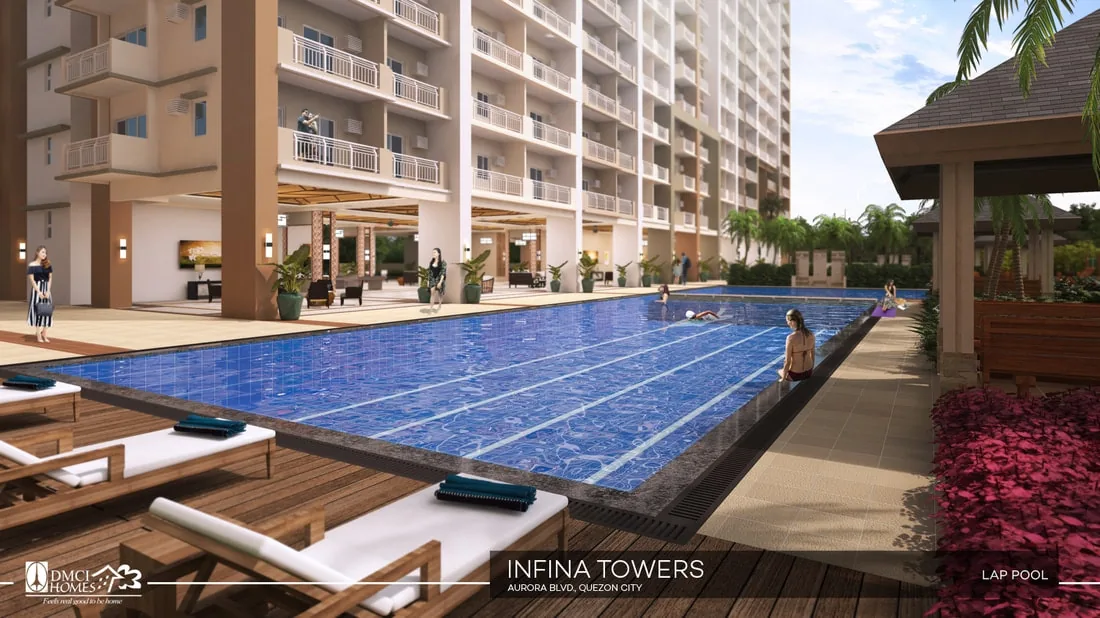
Infina Towers' twin 41-storey towers pair resort-style amenities with earth-toned interiors.
Current Promos
Infina Towers qualifies for DMCI Homes' RFO move-in promo and the Home Advance rent-to-own program.
Infina Towers qualifies for DMCI Homes' 5% downpayment promo — a ready-for-occupancy home with the lightest entry cost of the year.
| Promo Term | Discount | DP Period | Financing |
|---|---|---|---|
| 5% DP · 95% balance thru bank financing | 2% OFF | 12 months | Chinabank & BPI only |
Also Available · DMCI Modified Third Quarter Deal · Until October 31, 2026
12% DP / 32 months — 1% Discount
Reserve by October 31, 2026 and spread your 12% downpayment over 32 months with a 1% discount on your unit. Balance of 88% via bank or in-house financing. Special discounts apply to units only and are not combinable with regular discounts; parking may follow the same promo payment term as the unit.
Promo validity: June 1 – November 30, 2026 · per DMCI memo PD-26-05-028 (5% DP – 95% BF payment term extension, Chinabank & BPI financing only). Third Quarter Deal: valid June 1 – August 31, 2026 per DMCI memo PD-26-07-031. Final figures are confirmed at reservation — talk to Francine Baniqued to avail.
Infina Towers qualifies for the DMCI Homes Home Advance (Rent-to-Own) program. Move into your unit and lease it while you complete payment — instead of waiting for full bank financing.
Monthly HomeAdvance Lease Rates — Infina Towers
| Unit Type | Approx. Size | Monthly Lease | Move-In Cash-Out* |
|---|---|---|---|
| 1-Bedroom | 27.5–36 sqm | ₱10,000 | ₱42,500 |
| 2-Bedroom | 48.5–67 sqm | ₱14,000 | ₱54,500 |
| 3-Bedroom | 81.5–89 sqm | ₱16,000 | ₱60,500 |
*Move-In Cash-Out = 1 month advance rental + 2 months security deposit + ₱12,500 one-time utility deposit. PMO turnover fees (joining fee + water service deposit) are FREE under the promo.
Pay the 4 months downpayment in one go to qualify right away. This advance is not subject to any extra discount and your schedule stays as-is.
Pay your downpayment monthly as scheduled. You qualify for Home Advance availment after your 4th monthly payment.
All terms enjoy FREE PMO turnover fees.
Promo validity: July 1 – September 30, 2026 · per DMCI memo PD-26-06-014. Lease rates are indicative and based on unit bedroom type & size; final figures are confirmed at reservation. Talk to Francine Baniqued to avail.
Three ways into the same unit at Infina Towers. The 5% low spot downpayment is the lightest entry cost of the year — and it hands the bank ₱290,508 more to carry, which at an indicative 8.5% over 20 years works out to about ₱2,521 more every month, or roughly ₱605,064 more paid over the term. Home Advance keeps the smaller loan, carries the lightest monthly downpayment of the three, and is the only one that gets you into the unit before the bank releases anything.
| Infina Towers · North 512 | 12% Spot DP | 5% Low Spot DP | Home Advance 12% / 32 |
|---|---|---|---|
| Downpayment required | 12% | 5% | 12% |
| Promo discount | none | 2% | 1% |
| Net contract price | ₱4,858,000 | ₱4,760,840 | ₱4,809,420 |
| Downpayment amount | ₱582,960 | ₱238,042 | ₱577,130 |
| Payable over | 1 payment | 12 months | 32 months |
| Monthly downpayment | — | ₱17,337 | ₱17,098 |
| Cash to reserve + first payment | ₱582,960 | ₱47,337 | ₱47,098 |
| Cash out, first 12 months | ₱582,960 | ₱238,042 | ₱235,174 |
| Balance for bank financing | ₱4,275,040 (88%) | ₱4,522,798 (95%) | ₱4,232,290 (88%) |
| Est. amortization, 20 yrs | ₱37,100/mo | ₱39,250/mo | ₱36,729/mo |
| Bank options | any accredited bank | Chinabank or BPI only | any accredited bank |
| Earliest move-in | after bank drawdown | after bank drawdown | month 4 — before drawdown |
| Cash to reach move-in | ₱582,960 | ₱238,042 | ₱98,391 + ₱42,500 |
| While you finish the downpayment | your current rent | your current rent | ₱10,000/mo — your own unit |
| Who owns the unit from Day 1 | you | you | you |
Home Advance is not a “rent first, buy later” arrangement. The purchase happens first; the occupancy happens second. That order is everything:
Compare that with any arrangement where you lease first and the purchase is a separate, later decision that is subject to approval. There, you can pay faithfully for a year and still not own anything — and if the conversion is not approved, every peso you paid was rent.
Straight about the lease: under Home Advance you do sign a lease and the monthly Home Advance rate is not credited to your purchase. It is the occupancy fee for living in a unit you have already bought, before the bank releases the balance. Your ownership runs on the downpayment, in parallel — and it started the day you reserved. The right comparison is not “lease versus equity,” it is “this lease versus the rent you are paying someone else right now.”
Computed on North 512 — the lowest-priced available 1BR at Infina Towers (29 sqm, list ₱4,858,000) as of this page’s build date — with a ₱30,000 reservation fee. The 12% spot column assumes DMCI’s regular term with no promo discount applied; special discounts are tied to their own payment terms and are not combinable (memo PD-26-07-031). 5% low spot downpayment per memo PD-26-05-028, valid June 1 – November 30, 2026, Chinabank or BPI financing only. Home Advance per memos PD-26-06-014 and PD-26-06-020, valid July 1 – September 30, 2026. Bank amortization is an estimate at 8.50% over 20 years — your actual rate is set by your bank at approval. Closing fees are payable separately on all three routes.
Why Infina Towers
The developer inventory for this community is fully sold, but resale units and comparable DMCI communities are often available. Let Francine find the right fit for you.
Resale & assume-balance units — Francine monitors the secondary market for verified resale listings in this community.
Similar available communities — Get matched with comparable DMCI projects in the same area and price range.
Full buyer guidance — End-to-end help with reservation, financing, and documentation — zero agent fee to buyers.
Trusted DMCI accredited agent — Serving Filipino families and OFW investors since 2026.
Get in Touch
Talk to Francine Baniqued — your DMCI Accredited Agent — for the complete price list, unit availability, and a free personalized consultation.

DMCI Homes Property Consultant
DMCI Homes Accredited · Since 2026
Chat on WhatsApp →Tap below for a free, personalized property match — Francine replies within 5–10 minutes.
Get My Free Property Match →Common Questions
You are the buyer from Day 1. Home Advance at Infina Towers is not a rent-first arrangement — you reserve and sign a Contract to Sell on that specific unit before any occupancy begins, and every peso of your downpayment is equity in that purchase. The unit leaves the market the day you reserve and your price is locked at your contract price. There is no later conversion step and no separate approval needed to make you an owner, because you already are one; the only approval remaining is the bank loan on the balance, which every buyer on every payment term goes through. The Home Advance lease covers occupancy of a unit you have already bought while the balance is processed for bank drawdown, and that lease payment is not credited to the purchase — your ownership runs on the downpayment, in parallel.
On North 512, a 29 sqm 1BR at Infina Towers listed at ₱4,858,000: the 12% spot downpayment asks ₱582,960 in one payment and leaves a bank loan of ₱4,275,040. The 5% low spot downpayment needs ₱47,337 to start and ₱17,337 a month for 12 months, but leaves a bank loan of ₱4,522,798. Home Advance needs ₱47,098 to start and ₱17,098 a month for 32 months, and leaves the smallest bank loan of the three at ₱4,232,290 — about ₱2,521 a month less than the 5% route at an indicative 8.5% over 20 years.